Exponentially-Fitted Simpson’s Rule for Present Value Estimation
Introduction to Computational Mathematics — Spring 2026, with Robert Enright and Luke Baker
Overview
Present value calculations require integrating a cash flow stream against an exponential discount factor,
\[ PV = \int_0^T C(t)e^{-rt}\,dt. \]
Standard quadrature methods approximate the entire integrand using polynomial bases without taking advantage of this known exponential structure. For this project, we developed a modified Simpson’s rule that incorporates the discount factor directly into the quadrature basis.
Method
We derived the modified quadrature weights by solving a 3×3 linear system over the endpoints and midpoint of each integration panel. The resulting method recovers standard Simpson’s rule as the discount rate approaches zero and integrates functions in its fitted exponential basis exactly.
We compared the method with the Trapezoidal and standard Simpson’s rules on exponential, smooth, and oscillatory cash flows over a range of panel counts.
Results
Across all three cash-flow types, the exponentially-fitted rule produced lower numerical error than standard Simpson’s rule at the same step size.
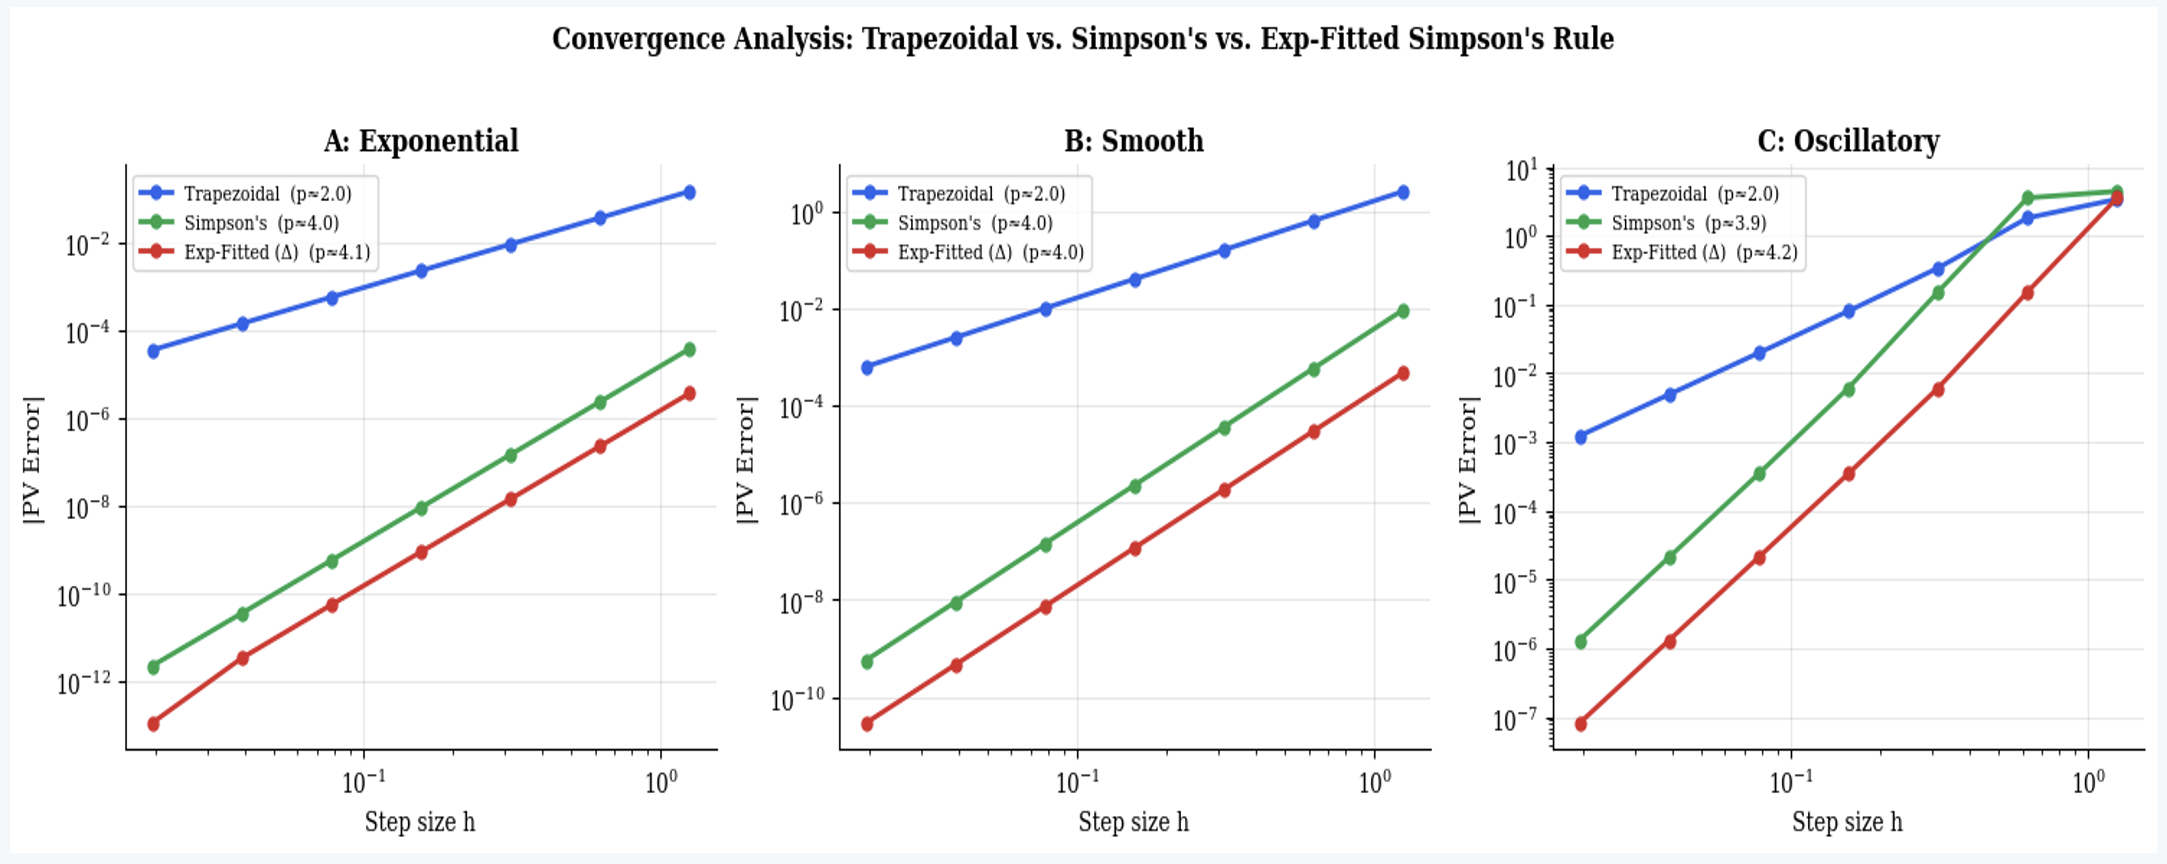
The largest improvements occurred for the exponential and smooth cash flows, where the fitted basis closely matches the structure of the integrand. The advantage narrowed for the oscillatory case, where that assumption is less appropriate.
Skills used
Numerical analysis · Quadrature methods · Python · Linear algebra · LaTeX